Life insurance is an important financial protection tool for individuals and families in the United States. It can provide money to beneficiaries after the insured person’s death, helping them manage expenses such as housing costs, education, debts, childcare, and everyday living expenses.
Choosing life insurance can seem complicated because there are different policy types, coverage amounts, premiums, exclusions, and application requirements. Understanding the basics can make the process much easier.
This guide explains how life insurance works in the USA, the major types of policies, factors that affect premiums, and important points to consider before purchasing coverage.
What Is Life Insurance?
Life insurance is a contract between an insurance company and a policyholder. The policyholder pays premiums according to the terms of the policy. In return, the insurer may provide a death benefit to the policy’s beneficiaries when the insured person dies, subject to the policy’s terms and applicable exclusions.
For example, suppose a person purchases a $500,000 life insurance policy and names their spouse as the beneficiary. If the insured dies while the policy is active and the claim qualifies under the policy terms, the insurance company may pay the beneficiary the $500,000 death benefit.
The money can generally be used for financial needs such as:
- Mortgage or rent payments
- Funeral and final expenses
- Credit card and other debts
- Children’s education
- Household expenses
- Childcare costs
- Replacement of lost income
- Long-term financial planning
The purpose of life insurance is therefore not simply to provide a payout. It can help protect the financial stability of people who depend on the insured person’s income or financial support.
Why Do People Buy Life Insurance?
Not everyone has the same reason for purchasing life insurance. The appropriate amount and type of coverage depend on a person’s financial situation and goals.
Income Replacement
For many families, the primary reason for buying life insurance is income replacement. If a household loses one person’s income, surviving family members may struggle to maintain their existing lifestyle.
A life insurance benefit can provide financial resources while the family adjusts to the loss.
Mortgage Protection
Homeowners may consider life insurance to help protect their families from mortgage obligations. A sufficient death benefit could help surviving family members continue making housing payments or pay down other financial obligations.
Supporting Children
Parents often consider life insurance because children may depend on them financially for many years.
A policy can potentially provide funds for childcare, education, housing, and other future expenses.
Paying Final Expenses
Funeral and other final expenses can create an additional financial burden for a family. Some people purchase smaller policies specifically to help cover these costs.
Business Planning
Business owners may also use life insurance as part of certain business-planning arrangements. Depending on the circumstances, coverage can help address financial obligations associated with the death of an owner or key person.
Business-related insurance arrangements can be complex, so professional legal and tax advice may be appropriate.
Main Types of Life Insurance
Life insurance policies in the USA generally fall into two broad categories: term life insurance and permanent life insurance.
Permanent insurance includes several types, such as whole life and universal life policies.
Term Life Insurance
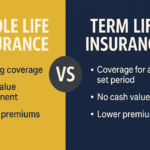
Term life insurance provides coverage for a specified period, such as 10, 20, or 30 years.
If the insured person dies during the covered term and the policy is in force, the insurer may pay the death benefit to the beneficiaries according to the policy terms.
One reason people consider term insurance is that it can provide substantial coverage without requiring the policyholder to purchase permanent coverage.
Term life insurance may be considered by people who want to protect their families during specific financial periods, such as:
- The years before children become financially independent
- The period remaining on a mortgage
- Working years before retirement
- A period when a spouse depends heavily on household income
However, term policies have expiration dates or other provisions that should be understood before purchasing.
Whole Life Insurance
Whole life insurance is a type of permanent life insurance designed to provide coverage for the insured’s lifetime, provided the policy remains in force and its requirements are met.
Many whole life policies also have a cash value component that can grow according to the policy’s terms.
Whole life insurance typically costs more than basic term insurance because it provides lifetime coverage and may include additional financial features.
Universal Life Insurance
Universal life insurance is another form of permanent coverage. Depending on the policy, it may provide flexibility in premium payments and death benefits while also having a cash value component.
Universal life products can be more complicated than term insurance because policy performance, charges, interest credits, and other factors can affect the policy.
Consumers should carefully review policy illustrations and contractual terms rather than relying only on projected future values.
How Much Life Insurance Do You Need?
There is no single coverage amount that is appropriate for everyone.
A useful starting point is to consider the financial responsibilities that would remain if you died.
You may want to consider:
- Your current income
- Outstanding debts
- Mortgage balance
- Number and age of dependents
- Children’s future education expenses
- Household living expenses
- Existing savings and investments
- Employer-provided life insurance
- Existing individual insurance policies
- Financial goals of your family
For example, a person with young children, a mortgage, and a single household income may have different coverage needs from a single person with substantial savings and no dependents.
Some people use an income-replacement approach, while others calculate their expected financial obligations and subtract assets that could be available to their family.
The important point is to look at the overall financial picture rather than choosing a coverage amount simply because it is a common number.
What Determines Life Insurance Premiums?
Insurance companies consider several factors when determining premiums.
Age
Age is an important factor because the likelihood of death generally increases as people get older. Purchasing coverage earlier may therefore result in lower premiums than purchasing similar coverage at a later age, although individual pricing varies.
Health
Health information can influence underwriting and pricing. Depending on the policy and insurer, an applicant may be asked questions about medical history, medications, lifestyle, and existing health conditions.
Some policies may require a medical examination, while others may use simplified or accelerated underwriting.
Tobacco Use
Tobacco and nicotine use can significantly affect life insurance pricing. Applicants should provide accurate information during the application process.
Misrepresenting tobacco use or other important information can create problems with a future claim.
Coverage Amount
A larger death benefit generally means a higher premium because the insurer is accepting a larger potential financial obligation.
Policy Length
For term insurance, the length of the coverage period can influence premiums. A 30-year policy may cost more than a comparable 10-year policy.
Occupation and Lifestyle
Certain occupations and activities may receive additional underwriting consideration because of associated risks.
Insurance companies may also consider information about activities such as certain high-risk recreational pursuits.
What Is a Life Insurance Beneficiary?
A beneficiary is the person or entity designated to receive the life insurance death benefit after the insured’s death, subject to the policy’s terms.
Common beneficiaries include:
- Spouse
- Children
- Parents
- Other family members
- Trusts
- Certain organizations or entities
Policyholders should keep beneficiary information updated, especially after major life events such as marriage, divorce, the birth of a child, or a change in family circumstances.
Beneficiary rules can vary depending on state law and individual circumstances, so complex situations may require professional advice.
What Is a Life Insurance Medical Exam?
Some life insurance applications involve a medical examination as part of the underwriting process.
Depending on the insurer and policy, an exam may include:
- Height and weight measurements
- Blood pressure
- Medical history questions
- Blood or urine testing
- Information about medications and medical conditions
Not every life insurance policy requires a traditional medical exam.
Some insurers offer policies using accelerated or simplified underwriting, although eligibility and pricing depend on the applicant and policy.
No-Exam Life Insurance
No-exam life insurance generally refers to policies where the applicant does not undergo a traditional medical examination.
However, “no exam” does not necessarily mean “no health questions.”
An insurer may still review information from the application and other permitted sources when evaluating an applicant.
Some no-exam policies may have lower coverage limits or higher premiums than fully underwritten policies.
Applicants should compare the actual policy terms instead of assuming that no-exam coverage is automatically cheaper or better.
How to Compare Life Insurance Policies
Comparing policies involves more than looking at the monthly premium.
Consider the following factors:
1. Coverage Amount
Check whether the death benefit is sufficient for the financial needs you want to address.
2. Policy Duration
For term insurance, understand exactly how long the coverage lasts and what happens when the term ends.
3. Premium
Compare the premium and understand whether it is guaranteed or subject to change.
4. Policy Features
Review available riders, conversion options, cash value provisions, and other features where applicable.
5. Exclusions and Limitations
Read the policy carefully to understand situations where benefits may be limited or excluded.
6. Financial Strength of the Insurer
Consumers may also research the financial strength of an insurance company using independent financial-strength rating organizations.
7. Beneficiary Rules
Make sure the policy allows you to designate beneficiaries in a way that fits your financial planning needs.
Common Life Insurance Mistakes
Buying life insurance without understanding the policy can create unnecessary problems.
Buying Too Little Coverage
A policy may appear affordable but fail to provide sufficient protection for the family’s financial obligations.
Choosing Only Based on Price
The cheapest premium does not necessarily provide the features or coverage that match your needs.
Forgetting to Update Beneficiaries
Major life events can change financial relationships. Beneficiary designations should be reviewed periodically.
Not Reviewing Employer Coverage
Some employees receive life insurance through their employer. While this coverage can be valuable, it may not be enough to meet all of a family’s financial needs.
Employees should understand what happens to employer-sponsored coverage if they change jobs.
Providing Inaccurate Information
Applicants should answer insurance questions honestly and completely. Incorrect information can create complications during underwriting or claims.
When Should You Buy Life Insurance?
There is no universal age at which everyone should purchase life insurance.
It may become particularly important when another person begins depending on you financially.
Common situations include:
- Getting married
- Having children
- Purchasing a home
- Taking on significant debt
- Starting a business
- Becoming responsible for another family member
- Planning for long-term financial obligations
Someone without dependents may have different insurance needs from someone supporting a family.
How to Apply for Life Insurance in the USA
The application process varies by insurer, but it commonly involves several stages.
Step 1: Determine Your Coverage Needs
Estimate the financial obligations you want the policy to address.
Step 2: Compare Policies
Research different insurers and policy types.
Step 3: Submit an Application
The application typically asks for personal, financial, and health-related information.
Step 4: Underwriting
The insurance company evaluates the application and determines eligibility and pricing based on its underwriting process.
Step 5: Review the Offer
If approved, review the proposed coverage, premium, exclusions, riders, and other policy details carefully.
Step 6: Put the Policy in Force
After completing the required steps and paying the applicable premium, coverage can become active according to the policy terms.
Final Thoughts
Life insurance can play an important role in financial planning for families and individuals in the United States. The right policy depends on factors such as income, dependents, debts, age, health, financial goals, and the type of protection required.
Term life insurance can provide coverage for a defined period, while permanent policies can provide longer-term coverage and may include cash value features. Each option has different costs and contractual provisions.
Before purchasing a policy, compare the coverage amount, premium, duration, exclusions, policy features, and financial strength of the insurer. Reading the actual policy documents is also important because specific terms can vary between insurance companies and products.
Life insurance is a financial product, not a one-size-fits-all solution. Consumers with complicated financial, tax, estate, or business situations may benefit from advice from appropriately licensed professionals who can consider their individual circumstances.